PROVIDING TAILORED BENEFIT SOLUTIONS SINCE 1986
GROUP PRODUCTS
In our highly competitive economy, being able to offer your employees exceptional benefit packages is a key component in good management. Let MFC Benefits
create the perfect customized package for your company.
Learn More
BENEFIT SERVICES
From informational seminars to programs tailored to your company's needs, we offer a wide range of benefit services. Let us help you provide your staff with the benefits they want and need.
Learn More
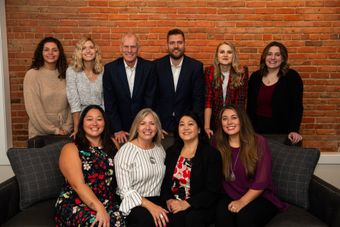
ABOUT US
The secret to our success is our team of professional benefits advisors and service representatives. Call us today at 248-663-4765 and we'll design, implement, and service an exclusive benefit package for your business.
Learn More
MISSION STATEMENT
Designing, implementing, and servicing exclusive benefit packages for you and your employees.
LATEST MEDIA
Learn more about cholesterol, if you are prepared for an emergency and meal prepping tips. CHOLESTEROL AND YOU Cholesterol is a substance in your blood that your body needs to build cells; yet, too much can pose a problem. Cholesterol travels through the blood on proteins called lipoproteins. There are two types: 1. Low-density lipoprotein (LDL), known as bad cholesterol , makes up most of your body’s cholesterol. High levels of LDL cholesterol can increase your risk for heart disease and stroke. 2. High-density lipoprotein (HDL), known as good cholesterol , absorbs cholesterol and carries it back to the liver to be flushed from the body. More than 40% of U.S. adults with high cholesterol—and 1 in 4 with very high levels— don’t know they have it, according to a study published in JAMA Cardiology. High cholesterol usually has no symptoms, so the American Heart Association (AHA) recommends that adults age 20 or older have their cholesterol checked every four to six years. Bad cholesterol can be elevated by age, family history, certain health conditions (e.g., Type 2 diabetes and obesity) and lifestyle factors. While you can’t control all of these factors, you can take steps to lower your risk: • Eat a heart-healthy, balanced diet. Saturated and trans fats can increase your cholesterol, so focus on monounsaturated fats (e.g., olive oil, nuts and avocados) and polyunsaturated fats (e.g., salmon and margarine). Also, limit red meat, fried foods, processed meats and baked goods. • Exercise regularly. The AHA recommends individuals get at least 150 minutes of moderate aerobic exercise each week. Adding resistance exercises to your routine at least twice a week can also help. • Avoid or quit smoking. Smoking tobacco increases LDL cholesterol, decreases HDL cholesterol and can result in cholesterol buildup in one’s arteries. • Limit alcohol use . For men, this typically means up to two drinks per day, and for women, one drink per day. • Maintain a weight that is healthy for you. Having obesity can increase your risk of high cholesterol. A doctor can help determine a sustainable weight management plan. The only way to know whether you have high cholesterol is to have your levels checked. Be sure to visit your doctor for regular cholesterol screenings. ARE YOU PREPARED FOR AN EMERGENCY? Disasters such as hurricanes, tornadoes, floods and earthquakes can strike with little or no warning. Roads may become impassable, power could be out for days and emergency services might be overwhelmed. In these situations, having a plan can make all the difference between chaos and calm. September is National Preparedness Month. As such, consider using this time to plan for scenarios that may require you to evacuate your home or shelter in place. Preparedness isn’t just about stocking up on supplies; it’s about knowing what to do, where to go and how to stay safe. Consider these four key steps to help you and your household prepare: 1. Know your risks . Understand the types of disasters most likely to affect your area. 2. Create a communication plan. Make sure every member of your household knows how to reach each other during an emergency. 3. Assemble an emergency kit. Your kit should include nonperishable food and water (enough for at least three days), flashlights and extra batteries, basic first-aid supplies, medications and personal hygiene items, important documents (e.g., IDs and insurance papers) in a waterproof container, and a battery-powered radio. 4. Plan for evacuation and shelter-in-place orders . Know your local evacuation routes and shelters. Also, prepare for scenarios in which you may need to stay indoors for several days. Visit Ready.gov to learn more about preparing for emergencies at home, at work and on the road. MEAL PREPPING TIPS September brings a shift in routine as school schedules kick back in and free time shrinks. Meal prepping is the concept of preparing meals for the week ahead. It can lead to more nutritious choices and help save valuable time on busy weeknights. HelloFresh's State of Home Cooking report revealed that 38% of Americans don't have groceries on hand when they need them, which is one of the biggest obstacles to making dinner. Fortunately, meal prepping can help solve that problem. Consider these best practices: • Stick to a schedule for when you plan, grocery shop and prepare your meals. • Pick recipes with varying cooking methods (e.g., oven or stovetop). • Choose which meals to prepare first based on their cook times. • Store meals properly in portioned containers. Refrigerate meals you plan to eat within three to four days and freeze the rest. Meal prepping doesn’t have to be intimidating. Try these basic steps to cut down on cooking time and have more time for other activities. This article is intended for informational purposes only and is not intended to be exhaustive, nor should any discussion or opinions be construed as professional advice. Readers should contact a health professional for appropriate advice. © 2026 Zywave, Inc. All rights reserved. Download the PDF copy here.
Learn more about the IRS releases pay-or-play affordability percentage for 2027 and the DOL proposes to expand electronic delivery options for group health plans. IRS RELEASES PAY-OR-PLAY AFFORDABILITY PERCENTAGE FOR 2027 On July 21, 2026, the IRS released Revenue Procedure 2026-26 to index the contribution percentage in 2027 for determining the affordability of an employer’s health plan under the Affordable Care Act (ACA). For plan years beginning in 2027, employer-sponsored coverage will be considered affordable under the ACA’s “pay-or-play” rules if the employee’s required contribution for selfonly coverage does not exceed 10.22% of their household income for the year. This is an increase from the affordability contribution percentage for 2026 (9.96%) and the highest it has ever been. Applicable large employers (ALEs) will need to consider this affordability percentage in developing their health plan contribution strategies for the 2027 plan year. ALEs may be able to increase employees’ health coverage contributions for 2027 while still meeting the adjusted affordability percentage. As background, the ACA’s pay-or-play rules require ALEs to offer affordable, minimum-value health coverage to their full-time employees (and dependents) or risk paying a penalty. The affordability of health coverage is a key point in determining whether an ALE may be subject to a penalty. An ALE’s health coverage is considered affordable if the employee’s required contribution to the plan does not exceed 9.5% (as adjusted annually) of the employee’s household income for the taxable year. Because an employer generally will not know an employee’s household income, the IRS has provided three optional safe harbors that ALEs may use to determine affordability based on information that is available to them: the Form W-2 safe harbor, the rate of pay safe harbor and the federal poverty level safe harbor. DOL PROPOSES TO EXPAND ELECTRONIC DELIVERY OPTIONS FOR GROUP HEALTH PLANS On July 23, 2026, the U.S. Department of Labor (DOL) issued a proposed rule that would establish a new, additional safe harbor for group health plan administrators to use electronic media to furnish plan disclosures required under the Employee Retirement Income Security Act (ERISA). The proposal aims to modernize the delivery of group health plan disclosures to reduce administrative burdens and improve participants’ ability to access and understand plan information. To rely on the safe harbor, plan administrators would be required to: • Provide an initial notification to each covered individual, identifying the electronic address to be used, explaining how to access covered documents, and describing their right to opt out of electronic delivery and request free paper copies; • Furnish a notice of internet availability for each covered document informing covered individuals of their paper copy and opt-out rights; • Establish and maintain a website where covered individuals can access covered documents, taking measures reasonably calculated to ensure the site meets specified standards for timing, presentation and confidentiality; and • Provide a free paper copy of any covered document promptly upon request. The proposed safe harbor does not permit email delivery because many ERISA group health plan disclosures contain sensitive information, including protected health information. Until the rule is finalized, plan administrators should continue to comply with existing disclosure requirements. Provided to you by MFC Benefits, LLC © 2026 Zywave, Inc. All rights reserved Download the PDF copy here.
Happy Customer Reviews
Memberships